BNN Bloomberg: Kai Lam on the surging bond market
What’s Driving Bond Yields Higher — and What Could Stop the Rise?
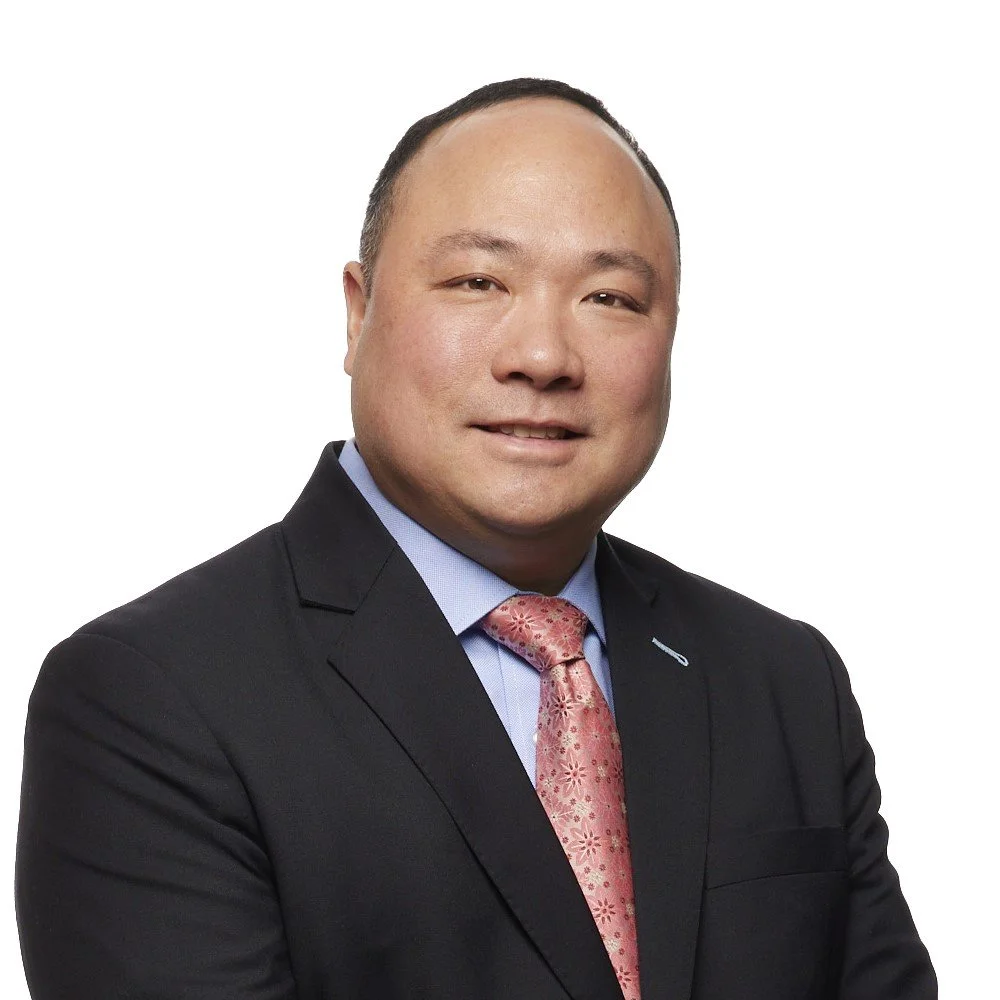
In a recent appearance on BNN, Kai Lam explained some of the forces behind the increase in bond yields.
Bond yields have been climbing as investors contend with persistent inflation, geopolitical uncertainty and an increasing supply of new debt. But JCIC Chief Investment Officer Kai Lam sees several factors that could ultimately put a ceiling on yields.
“The bond yields have been rising for a few different reasons,” Lam explains. Inflation remains elevated, while tensions in the Middle East have pushed oil prices higher. At the same time, Canada-U.S. tariffs are adding to inflationary pressures.
Supply is another factor. Lam points to “a lot of AI-related corporate issuance,” while governments continue issuing bonds to finance deficits. Greater supply can put downward pressure on bond prices and, in turn, push yields higher.
There are, however, potential limiting factors. Progress in the Middle East could bring oil prices back down, easing an important source of inflation. Lam also believes the labour market may be softer than headline numbers suggest, pointing to declining labour-force participation and slowing U.S. wage growth.
Combined with improving productivity, partly attributable to AI, these trends could reduce inflationary pressure.
“I think inflation can come down or at least peak out,” Lam says, “and that could stabilize the bond rates right now.”
Disclosure: Although we obtain information contained in our newsletter from sources we believe to be reliable, we cannot guarantee its accuracy. The opinions expressed in the newsletter are those of JCIC Asset Management, its editors and contributors, and may change without notice. Any views or opinions expressed in the newsletter may not reflect those of the firm as a whole. The information in our newsletter may become outdated and we have no obligation to update it.
The information in our newsletter is not intended to constitute individual investment advice and is not designed to meet your personal financial situation. It is provided for information purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. No recommendation or advice is being given as to whether any investment is suitable for a particular investor or a group of investors. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable.
We strongly advise you to discuss your investment options with your Relationship Manager prior to making any investments, including whether any investment is suitable for your specific needs.
The information provided in our newsletter is private, privileged, and confidential information, licensed for your sole individual use as a subscriber. JCIC Asset Management reserves all rights to the content of this newsletter.